Industrial & Manufacturing
Founder-owned precision machining company
has been acquired by
a strategic aerospace components supplier
Exclusive sell-side advisor
2026
Headquartered in San Jose, California. Advising B2B companies across North America.
We advise owners of precision manufacturers, engineered-product companies and industrial service businesses on sales, acquisitions and recapitalizations. Each process is built around how a buyer will read your customer concentration, capacity and margin history.
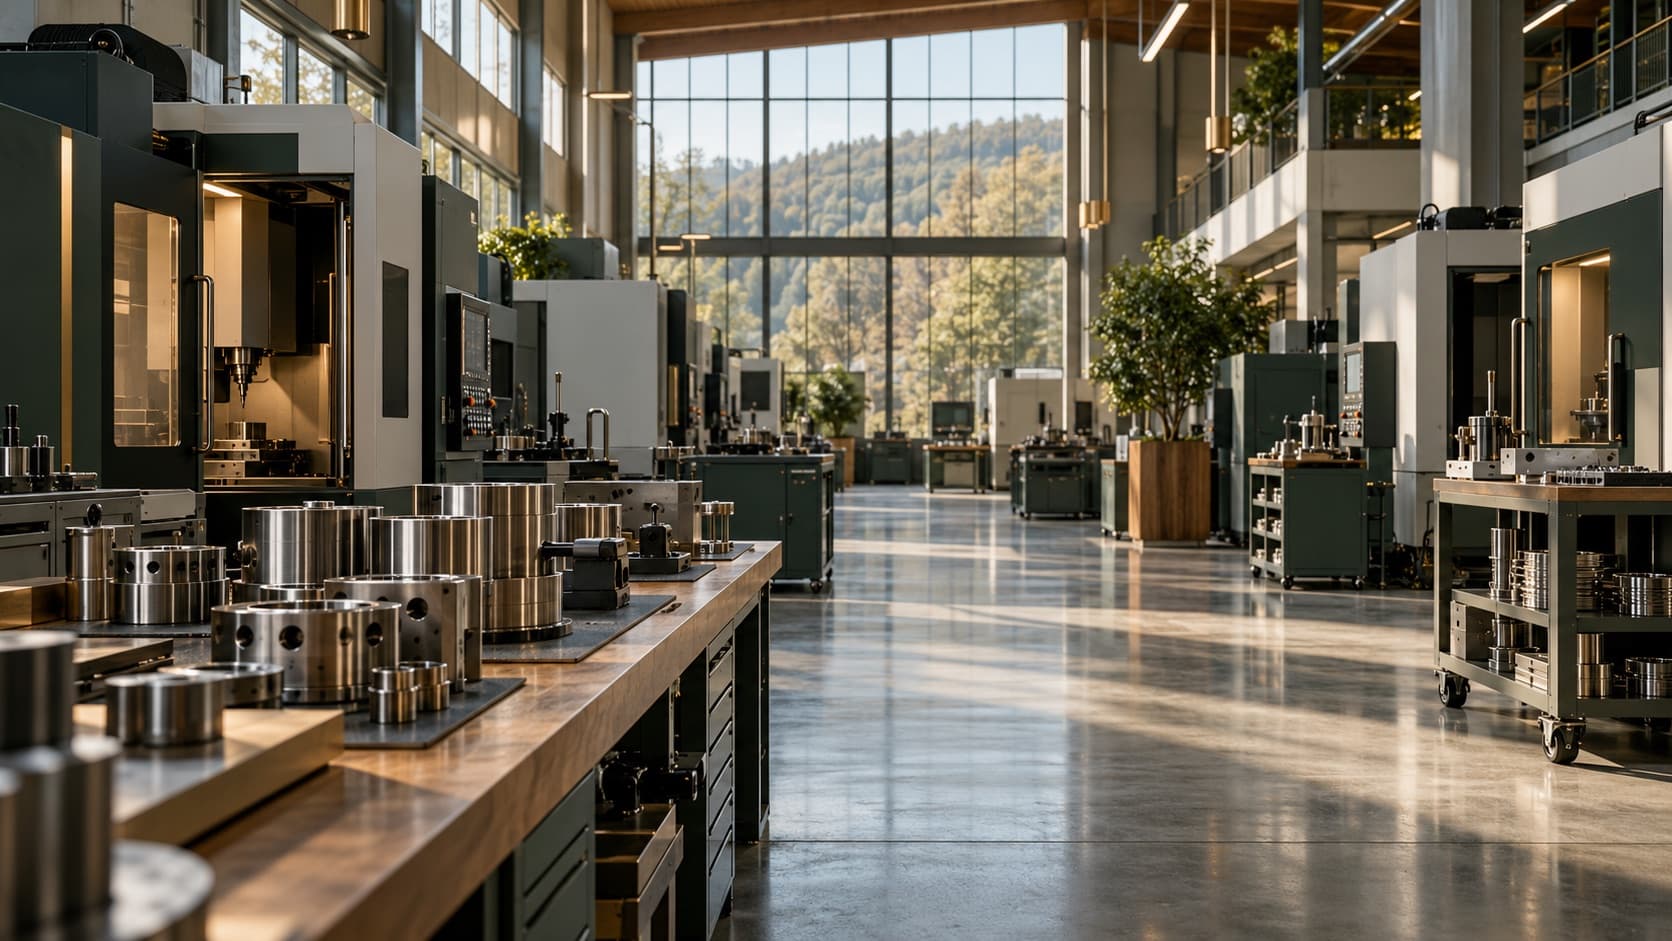
Customers that moved component sourcing offshore a decade ago are qualifying domestic and nearshore suppliers to shorten lead times and reduce exposure to tariffs and freight disruption. Acquirers are paying for North American capacity that already holds the certifications and customer approvals this shift requires.
Skilled labor on the shop floor remains the binding constraint for most manufacturers. Businesses that have invested in robotics, unattended machining or a modern ERP tend to hold margins through volume swings, and buyers increasingly underwrite that operating discipline rather than headcount growth.
A large share of lower middle market manufacturers were built by owners now approaching retirement, often without a family successor. That supply of well-run businesses meets steady demand from platforms seeking add-ons, which keeps the market active even when broader deal volumes soften.
Buyers now separate original equipment revenue from replacement parts, repair and field service, which is typically less cyclical and carries higher margins. Companies that can show the installed base behind their aftermarket revenue often receive a meaningful premium.
Industrial businesses are rarely valued on last year’s earnings alone. Buyers want to know how those earnings behave across a cycle, what share of them depends on a handful of customers, and how much capital the plant will need over the next five years. A sale process that answers those questions before they are asked tends to hold its value through diligence.
Many manufacturers show a strong recent year driven by pricing actions, a large program or restocking demand. Experienced buyers will look through that to a multi-year average. We prepare a view of revenue and margin by end market and by customer over at least three to five years, separate one-time programs from run-rate work, and document which pricing and cost actions are durable. This puts the owner’s account of the business on the same footing as the buyer’s quality-of-earnings work, rather than leaving the buyer to construct its own.
Real estate is often held separately by the owner and can be sold with the business or leased back at a market rent, which changes both proceeds and the earnings a buyer is valuing. Founders who intend to stay through a transition may prefer a partial sale or a rollover into a sponsor platform, keeping a stake in a second exit. We model these alternatives side by side so the decision rests on after-tax outcomes and risk, not on headline price.
Our sourcing platform maps strategic and financial buyers by process capability, certification and end market rather than by industry code alone. That distinction matters in manufacturing, where the most motivated buyer is often a company in an adjacent niche that needs a specific capability, not the obvious competitor down the road.
Approved-vendor status, first-article or PPAP approvals and specified designs that make it costly and slow for a customer to switch suppliers.
AS9100, ISO 13485, ITAR registration and similar credentials that take years to earn and screen out most competitors.
No single customer much above 15 to 20 percent of revenue, and exposure balanced between cyclical and defensive end markets.
Proprietary designs, application engineering and value-added assembly rather than pure build-to-print work priced on machine hours.
Equipment in good repair and open capacity on existing shifts, so a buyer is not facing an immediate capital program to support the forecast.
Larger manufacturers buy to add a process capability, a certification, regional footprint or a customer relationship they cannot win organically. They tend to pay most when the target fills a specific gap that can be sold through their existing channels.
Sponsors typically look for several million dollars of EBITDA, a capable second layer of management and a clear runway for add-on acquisitions. They focus on the durability of margins through a cycle and the reliability of the financial reporting.
Sponsor-backed platforms already in the space pursue smaller manufacturers for capacity, adjacent processes or customer access. They can be flexible on size and often offer founders a rollover stake in the larger combined company.
Industrial & Manufacturing
has been acquired by
a strategic aerospace components supplier
Exclusive sell-side advisor
2026
Industrial & Manufacturing
has acquired
a founder-owned plastics molder as a platform investment
Buy-side advisor
2024
Concentration does not prevent a sale, but it shapes price and structure. Buyers will want to understand the length of the relationship, whether you are sole-sourced, the contractual terms and how the customer’s own demand is trending. Where concentration is high, part of the consideration is sometimes tied to retention through an earnout or seller note; a well-documented relationship history can narrow that gap.
It depends on your tax position, the buyer and the property. Many sponsors prefer not to own real estate and will sign a long-term lease at a market rent, which leaves you with a separate income-producing asset. Strategic buyers are sometimes more willing to purchase it. We evaluate both paths, including the effect of a market rent on the earnings being valued.
Investment that has expanded capacity or capability helps when you can show the return, either in margin improvement or in new work it has won. Buyers will also assess what remains to be spent. A plant that is current on equipment, with documented maintenance, removes a common reason for a price reduction late in diligence.
Valuation|
Size, revenue quality, the working capital peg, earn-outs, seller notes and rollover equity often matter as much to sellers as the headline multiple.
Sourcing|
Many of the best lower middle market acquisitions begin with an owner who was not selling. How direct, confidential outreach to owners works in practice.
Buy-Side|
Beyond the growth story, acquirers test net revenue retention, gross margin, cohort data, contract terms, technical debt and key-person risk.
Conversations with Laurent Capital are confidential and carry no obligation. A senior member of the firm responds to every inquiry within one business day.